Find the Opportunity
Understand who hires mobile notaries and why scope clarity wins.
A practical starting point for notaries who want to launch a mobile signing service with clearer client intake, scheduling habits, and compliance workflow basics.
This page walks you through how to start a mobile notary business as a professional commissioned service—not informal signings for friends without journal discipline or scope clarity. You will learn who hires mobile notaries, how to distinguish notary work from signing agent appointments, how to verify local law and maintain journal and ID standards, how to build signing workflow and pricing from real costs, how to win first signings, and how to grow with the operational discipline title partners and borrowers expect.
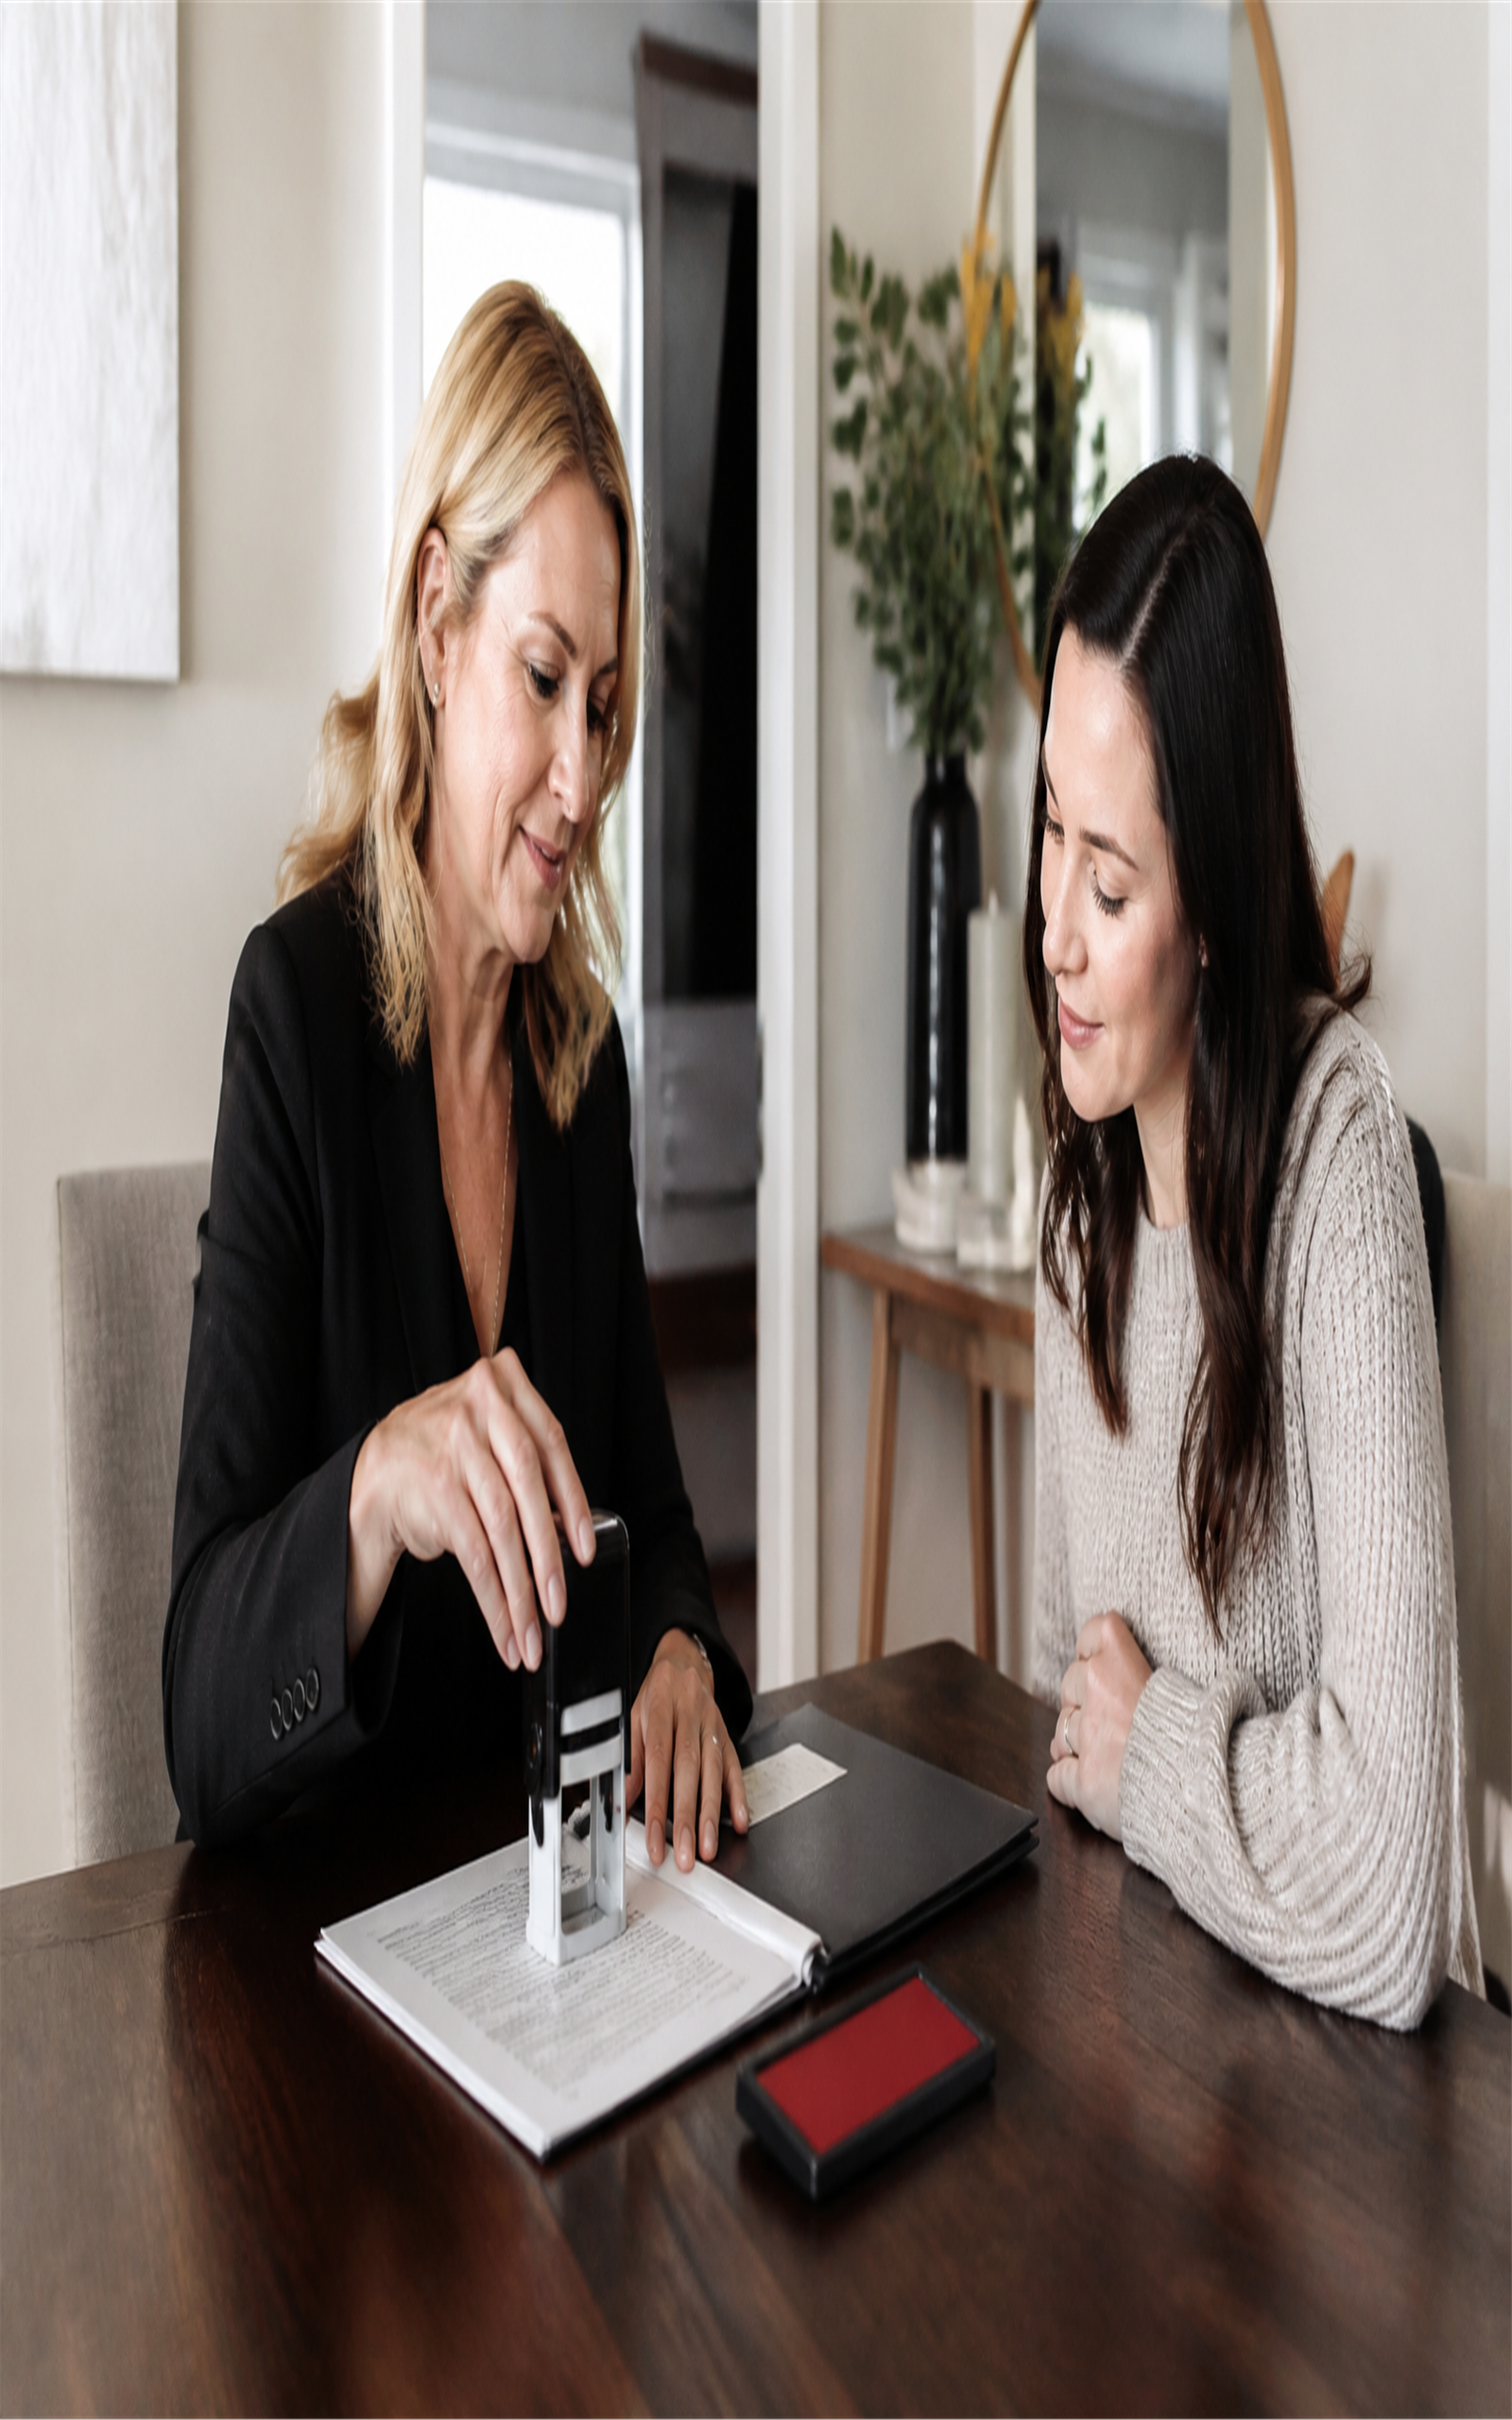
Understand who hires mobile notaries and why scope clarity wins.
Decide which appointment types you accept and what you refer out.
Verify commissioning rules, journal requirements, and ID standards locally.
Build a travel kit and repeatable signing routines for every appointment.
Quote signings from travel, duration, statutory limits, and overhead.
Reach title partners, signing services, and direct clients with a controlled launch.
Improve intake accuracy and add capacity only when workflows hold.
A mobile notary business delivers authorized notarial acts at the signer's location under written scope boundaries and documented compliance habits—not informal stamp-and-go appointments without identity verification or journal records. You screen each inquiry, confirm the appointment fits your commission and service menu, travel with the tools your workflow requires, verify signer identity per local rules, complete the notarial act correctly, and maintain records your state expects. Buyers pay for clarity about what will be notarized, when you will arrive, what identification signers need, and whether you handle loan packages or general notarial work only.
That distinction matters. Holding a notary commission is not the same as running a mobile notary business. Many commissioned notaries accept appointments without intake discipline, underprice travel time, confuse notary work with legal advice, or skip journal entries that protect them when questions arise later. Title companies, signing services, law offices, lenders, and individuals continue to hire mobile notaries when closings, affidavits, and time-sensitive documents need a reliable official on site—but only when they believe the notary will follow state rules, verify identity correctly, and communicate appointment details without surprises.
This guide walks you through how to start a mobile notary business with professional habits: finding your opportunity, distinguishing notary public work from signing agent appointments, verifying local law and maintaining journal and ID standards, building tools and signing workflow, pricing from real costs, winning first signings through structured client intake, and growing with the operational discipline that defines a credible mobile practice. By the end, you should understand what the business is, what you need to prepare, and what to verify locally before accepting your first booking.
Title companies, signing services, law offices, and individuals hire mobile notaries when documents must be signed where the signer is—not at a stationary office during business hours. Your first step is understanding who you serve and what they expect from a professional notary—not assuming your commission alone creates demand.
Mobile notary businesses succeed when clients understand the appointment before you travel: document type, number of signers, estimated duration, acceptable identification, fee structure, and what happens if documents are incomplete on arrival. Buyers are not simply purchasing a stamp—they are purchasing confidence that the notarial act will be performed correctly, recorded properly, and completed on schedule at hospitals, homes, offices, or closing tables.
Different clients bring different expectations, volume, and fee potential. Choose one primary profile for launch:
Often need loan signing agents for real-estate closings and refinances—appointments with large document packages, tight scheduling windows, and low tolerance for errors. Reliability, background screening readiness, and signing workflow discipline matter more than the lowest fee quote.
Need general notarial acts for clients who cannot visit the office—estate documents, affidavits, powers of attorney, and business acknowledgments. Clear intake, punctual arrival, and correct journal entries support repeat referrals from attorneys and paralegals.
Book mobile notaries for convenience at homes, workplaces, or care facilities. They compare on responsiveness, fee transparency, and guidance about required ID—not always on the lowest per-signature rate alone.
Observe your local market: who do existing mobile notaries and signing agents serve well, and where do partners still express frustration—late arrivals, incomplete journal entries, signers turned away for ID issues that should have been screened on the phone, or notaries who drift into document explanation they are not authorized to provide? Your opportunity often sits in operational clarity and compliance discipline as much as in holding a commission.
Mobile notary demand is rarely uniform across a week. Estate planning attorneys cluster signings around tax seasons and year-end planning. Real-estate closings follow market cycles in your area. Healthcare-related signings—advance directives, powers of attorney for elderly parents, and hospital-bed acknowledgments—often arrive with short notice and emotional urgency. Operators who communicate calmly under pressure and refuse to cut ID verification corners earn referrals in these moments; operators who rush or improvise lose them permanently.
Geography matters as much as client type. Rural areas may have few commissioned notaries willing to travel; suburban corridors may be saturated with signing agents competing on loan closing fees. Urban markets may offer volume but also stricter competition from established signing services. Map your service radius honestly: a forty-five-minute drive each way for a single acknowledgment may not sustain a business unless your fee structure and appointment clustering account for that reality from day one.
Professional service businesses with similar client-trust dynamics—such as those in the freelance business guide, consulting business guide, and grant writing business guide—show how defined scope, professional intake, and dependable delivery sustain independent service revenue. Mobile notary work follows the same pattern: clients hire operators they believe will show up prepared, stay within role boundaries, and finish the engagement correctly.
Practical takeaway: Write one paragraph describing your ideal first client and appointment type—general notarial acts, loan signings, or a mix with clear boundaries. List three questions they will ask before booking—and make sure your future intake process answers them.
Before you market mobile notary services, decide what you accept, what requires additional signing-agent training, and what you must never do—including legal advice and document preparation. Clients and partners need role clarity, not a vague promise to "handle documents."
A notary public is a state-commissioned official authorized to perform specific notarial acts defined by local law—typically including acknowledgments, jurats, oaths, affirmations, and copy certifications where permitted. The notary verifies identity, confirms willingness, completes the notarial certificate, and records the act as required. The notary does not explain document content, advise on legal consequences, or prepare documents unless separately licensed to do so.
A signing agent—sometimes called a loan signing agent—is generally a notary who additionally handles mortgage and real-estate closing packages for lenders, title companies, or signing services. That work often involves larger document sets, courier and return instructions, eSigning or hybrid closings where permitted, and platform-specific training or certification expectations. Signing agents still may not provide legal advice; they guide signers through the signing process according to instructions from the hiring party.
Acknowledgments, jurats, oaths, and copy certifications on affidavits, contracts, school forms, travel consent letters, and business documents—when allowed in your state. Best when you want flexible appointments without loan-package complexity at launch.
Real-estate purchase, refinance, HELOC, and reverse-mortgage packages from title companies or signing services. Requires comfort with large document sets, signing order discipline, and return/shipping workflows—not only a stamp.
Some jurisdictions allow remote online notarization or hybrid closings under specific rules, technology, and registration requirements. Treat these as separate service lines you add only after verifying local authorization—not as automatic extensions of a standard commission.
Legal advice, document drafting, explaining loan terms as an advocate, performing acts outside your commission geography, and appointments where signers lack acceptable ID or willingness. Naming these boundaries upfront protects signers and your commission.
Not every request fits your launch menu. Use intake questions to filter appointments early:
Written scope prevents the most common mobile notary disputes:
The consulting business guide emphasizes defining what you do and do not deliver before marketing—a lesson that applies directly here. A notary who accepts "any document" without screening invites scope creep, compliance risk, and appointments that run long because the signer was unprepared.
Practical takeaway: Draft a one-page service menu listing general notarial acts you accept, loan signing work you accept (if any), and five categories you decline or refer out. Read it aloud—if a caller would still ask "can you tell me if I should sign this?", add clearer language about role limits.
Notary law is state-specific—and sometimes county-specific for recording or filing details. Your investigation framework matters as much as your stamp: verify commissioning rules, journal obligations, and identity verification standards locally before marketing paid signings.
Create a checklist and confirm each item with your state's commissioning authority, notary handbook, and insurance agent. Requirements differ significantly by jurisdiction—do not assume rules from another state apply to you:
Your journal is part of your professional defense when a signing is questioned months later. Where required or recommended, record entries contemporaneously with the notarial act:
Use a bound sequential journal unless your state authorizes an electronic journal with specific standards. Never let clients or employers keep your journal. Store completed journals securely for the retention period your state requires.
Real signings rarely match textbook examples. Prepare written procedures—not improvised judgment—for recurring edge cases your state addresses:
Your obligations do not end when the signer leaves. Journal retention periods, commission renewal deadlines, bond continuity, and stamp replacement when your commission number changes are ongoing business responsibilities. Calendar renewal dates months in advance—a lapsed commission means every notarial act performed during the gap may be invalid. If you relocate or resign your commission, follow your state's journal transfer or deposit procedures rather than abandoning records in a drawer.
Use ID types your state notary handbook lists—often government-issued photo identification with signature. Confirm the ID is current if your state requires non-expired documents. Examine the physical ID; do not rely on photos sent ahead unless your jurisdiction allows a specific remote process.
When signers lack acceptable ID, some states allow one or two credible witnesses who know the signer and meet statutory requirements. Know the rules before the appointment—not at the kitchen table when the signer produces only an expired card.
Confirm the signer appears willing and aware of the transaction. Refuse the act if you suspect coercion, incapacity, or document problems you cannot resolve within your role—refer the hiring party to legal counsel when appropriate.
Separate business banking, written appointment terms, a basic bookkeeping routine, and documented cancellation policies protect you as much as your bond does. Decide whether title partners invoice you or signers pay at appointment, how last-minute cancellations are handled, and how you retain copies of certificates or platform records where allowed.
The SBA guide to launching a business helps with general registration and planning steps, but it does not replace your state notary handbook. Start your research early—some commissioning steps take weeks, and performing unauthorized acts can invalidate your commission and insurance coverage.
Practical takeaway: Download or order your state's current notary handbook and highlight journal and ID sections. Complete your verification checklist with dated notes from official sources—not forum posts. Do not accept loan signings until you understand both general notary duties and signing-agent workflow expectations.
A mobile notary business runs on two foundations: a travel kit matched to your accepted appointment types, and a signing workflow that turns bookings into completed acts without missed identity checks or journal steps. Under-prepared arrivals and improvised routines create compliance risk faster than any competitor's lower fee.
Assemble core supplies first; add loan-signing tools when you commit to that service line:
Track seal replacement, journal cost, and supply use in your pricing model. These are production costs on every appointment—not personal overhead you absorb silently.
Professional mobile notary work follows a repeatable sequence:
Title partners and signers notice details beyond the stamp impression:
Intake should collect gate codes, parking instructions, hospital room numbers, signer phone numbers, and whether a spouse or witness must be present. Surprises on arrival—missing signers, incomplete loan packages, or unacceptable ID—are costly when your calendar blocks travel time you cannot resell.
Mobile notaries work in homes, law offices, hospital rooms, coffee shops, parking lots, and occupied properties under sale. Assess each environment briefly on arrival: adequate lighting to inspect ID, a flat surface for documents, privacy to discuss signing without unauthorized listeners, and a personal safety exit plan when meeting strangers. Trust scheduling platforms and referral sources, but maintain situational awareness—especially for evening appointments or first-time clients in unfamiliar neighborhoods. Decline or reschedule signings in environments where you cannot verify identity properly or where you feel unsafe; no fee justifies commission risk or personal harm.
When you add signing agent scope, your workflow expands beyond a single acknowledgment:
Independent operators in adjacent fields—see the freelance business guide—benefit from the same intake discipline: confirm scope before you commit time. Mobile notary workflow is appointment-driven; one unprepared signing can consume an afternoon.
Practical takeaway: Pack your travel kit and run one practice appointment—even a mock general notarization—with your full workflow checklist. Note any second trip caused by missing supplies or skipped intake questions—and fix those before your first paid signing.
Clients and title partners buy dependable completion and correct compliance—not vague fees that ignore travel time or document complexity. Pricing should reflect statutory limits where applicable, the full cost of the documented appointment, and the margin that makes the business sustainable.
Consider every cost category that applies to your model:
Mobile notary work carries disproportionate travel cost. A single-signature appointment forty minutes away is not priced like a walk-in office signing next door. Build travel zones, minimum appointment fees, and loan-signing packages that cover mobilization honestly—partners prefer transparent fees over artificially low base rates with surprise travel surcharges later.
Use this framework as a starting model—adjust every figure against your state's fee caps, local market rates, and measured costs:
Publish fee language on your website and repeat it in appointment confirmations. Ambiguity about travel charges is one of the fastest ways to lose referrals from attorneys and title coordinators who expect invoicing clarity.
Per-act or per-signature pricing suits general mobile notary work with clear statutory caps. Flat loan-signing fees suit title and signing-service appointments where document volume and return instructions are known in advance—define what is included, what triggers a rescheduling fee, and how incomplete packages are handled.
Separate line items for extra signers, second trips caused by client error, and waiting time beyond a stated grace period help buyers understand the quote. Title coordinators especially appreciate fee sheets that map cleanly to their scheduling templates.
Include payment terms, cancellation windows, no-show policies, and what happens when signers lack acceptable ID on arrival. Notary time is route-locked; hours waiting on missing documents or absent co-borrowers are cost you cannot recover on another signing the same day.
Track actual drive time, appointment duration, and fee collected on every early booking against your estimate. Adjust zone pricing and loan packages based on real results rather than initial guesses. The grant writing business guide stresses the same discipline: sustainable pricing comes from documented engagement costs, not competitor guessing.
Practical takeaway: Build a pricing spreadsheet with per-act fees, travel zones, loan-signing packages, and overhead allocation. Complete it for your next three booking types, then compare projected costs to actuals after each appointment closes. Refine before scaling outreach to title companies.
Trust drives booking decisions in notary work. Title coordinators, signing services, and individual signers choose notaries who communicate clearly, verify identity correctly, and arrive prepared—not whoever quotes the lowest fee without intake discipline.
Avoid advertising without compliance discipline behind it. Clear ID requirements, visible commission credentials, reliable arrival windows, and error-free journal habits demonstrate professionalism better than discount fee messaging alone.
Attorneys and title coordinators remember notaries who solve problems without creating new ones. Return calls promptly. Send confirmation emails with fee, time, and ID requirements spelled out. Arrive early enough to review documents before the signer sits down. Never call an attorney for legal advice about a document—that is the client's role. When you decline a signing because ID is insufficient, explain calmly and offer to reschedule rather than arguing on site. When you accept a referral, invoice cleanly and thank the referrer after the appointment closes. One reliable mobile notary in an estate planning practice can receive dozens of signings per year; one sloppy journal entry can end the relationship permanently.
Keep initial outreach professional and scope-specific: introduce your commission status, geographic service area, general notary services you perform, travel fee structure, and availability windows. Offer to leave cards at a law office front desk or include your listing in a paralegal referral packet. Do not promise loan signing expertise you have not trained for; do promise journal accuracy and punctual arrival for general notarizations. Follow up once, then respect silence—persistent cold outreach reads as desperation, not professionalism.
Service businesses built on professional intake—such as those described in the consulting business guide and freelance business guide—show how structured discovery conversations convert interest into paid engagements. Your intake call is the notary equivalent: screen scope, confirm ID readiness, and set fee expectations before you drive.
Practical takeaway: Land your first three appointments through direct outreach to attorneys, title coordinators, or signing services who match your target profile—before spending on ads. Document every intake question they raise and refine your confirmation templates after each conversation.
Growth means adding appointment types and partners only when journal accuracy, identity verification, and intake screening stay consistent—not accepting every signing because your calendar has gaps.
A sensible progression:
Adding appointment volume introduces quality control risk. Review journal samples periodically, track failed signing rate, and monitor partner feedback monthly. One incorrect certificate or missed identity check can end a title relationship that took seasons to build.
Track metrics that matter: appointments per week, drive time per signing, failed appointment rate, repeat partner bookings, fee per hour including travel, and referral source—not vanity metrics like total directory views. Fix intake and compliance gaps before marketing harder.
Practical takeaway: After your first twenty completed signings, identify your most common intake miss and your strongest referral source. Fix the confirmation or ID-screening issue before adding loan signing volume or expanding your travel radius.
Use this four-week outline to move from interest to a controlled first signing. Each week builds on the last for a mobile notary business launch.
Confirm these essentials before you accept a booking or travel to your first paid mobile notary appointment.
A mobile notary business is a professional service where a commissioned notary public travels to clients to perform authorized notarial acts under written scope boundaries and documented intake habits. Success depends on knowing what acts you may perform, verifying signer identity correctly, maintaining required records, and communicating appointment details clients and title partners can trust.
A notary public is a state-commissioned official authorized to perform notarial acts defined by local law. A signing agent is typically a notary who additionally handles loan document signing packages for lenders, title companies, or signing services—often with extra training and workflow expectations. Define which work you accept before marketing.
You must hold an active notary commission and meet any bond, training, or registration requirements in the jurisdiction where you perform acts. Commission rules vary significantly by state. Verify requirements with your state's commissioning authority before accepting paid signings.
Follow your state's notary handbook for journal requirements, acceptable identification types, and credible-witness rules. Record each act with date, act type, signer information, and ID method. Verify identity at every signing using approved methods—not assumptions based on familiarity.
List the notarial acts and appointment types you accept and the work you decline or refer out, including legal advice and document preparation. Document scope on every booking: location, signer count, document type, estimated duration, and fees.
Build pricing from statutory fee limits where applicable, travel time and distance, appointment duration, after-hours premiums, and overhead. Test prices in a spreadsheet using your actual drive time and signing duration—not unverified rates from another market.
Follow a repeatable sequence: inquiry and scope screening, appointment confirmation, identity verification and journal entry, notarial act completion per state rules, payment collection, and secure record retention. Intake should capture ID readiness and access details before you travel.
Start with a defined client profile and controlled launch offer. Reach title companies, signing services, law offices, and individuals through directory listings, direct outreach, and referral partnerships. Professional intake forms and reliable scheduling convert interest faster than vague low fees alone.
This mobile notary business example was developed using eBook Business Builder—the workflow used to structure the guide, free lead magnet, offer assets, email series, and marketing content you see in the EBB Showroom below.
If you want to create your own eBook business around a topic you know, EBB walks you through research, writing, assets, and launch in a repeatable system. See how business assets fit together and launch marketing for your eBook business to understand the full EBB build model.
Start Building with eBook Business Builder →The flagship guide explains how to start a mobile notary service—notary scope boundaries, local law verification, journal and ID standards, signing workflow, pricing, and client communication—in a structured eBook format.
Chapters walk readers through evaluating the opportunity, distinguishing notary from signing agent work, verifying commissioning and journal rules, building travel kit and signing workflow, pricing from real costs, winning first signings through structured intake, and growing operations without sacrificing compliance discipline.
First Signings & Client Intake — a lead magnet that helps readers evaluate whether mobile notary work fits their goals and identify sensible first steps before accepting bookings.
Many commissioned notaries accept signings without intake discipline, journal habits, or scope boundaries that protect their commission and client expectations.
Foundational first steps, common early mistakes to avoid, and a simple action plan readers can use before committing to client bookings or service launches.
Has a notary commission but unsure how to distinguish notary work from signing agent appointments or run a mobile practice professionally.
Prepared with the fundamentals needed to screen bookings, verify local law, maintain journal and ID standards, and deliver dependable signings on schedule.
Mobile Notary Startup Program
A practical flagship guide for readers ready to move from interest to action—with clear first steps and professional service habits for dependable mobile notary work.
Tools & References